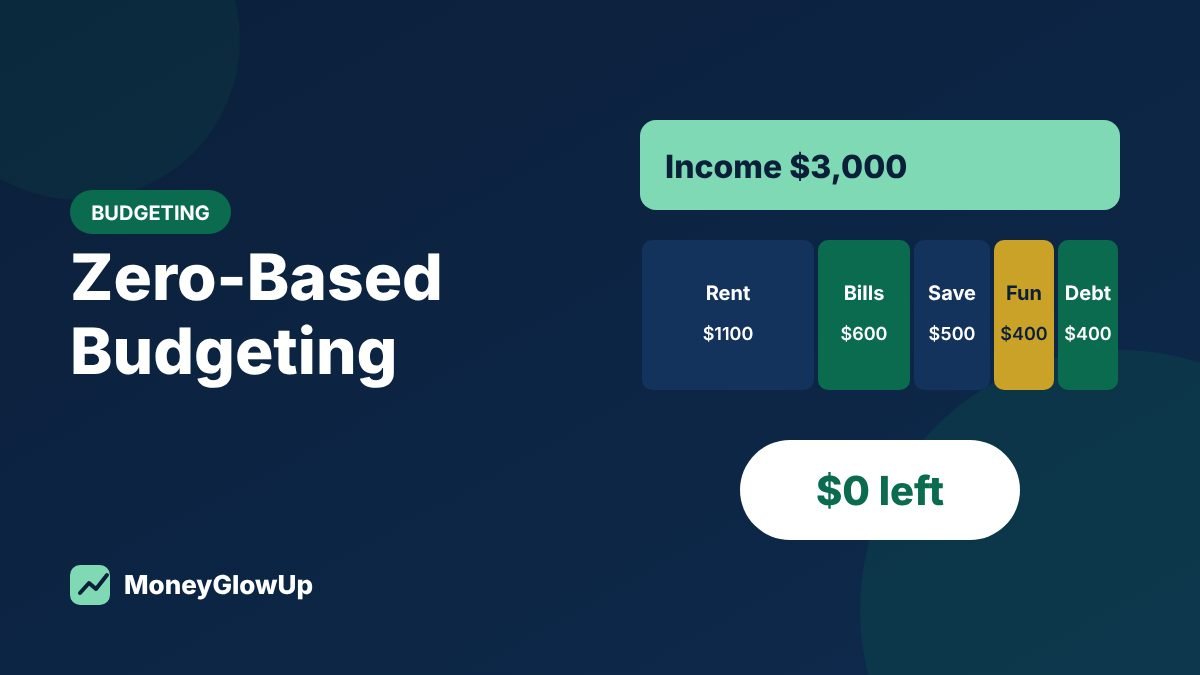
A zero-based budget means income minus everything you plan to spend, save and pay equals zero. It doesn’t mean spending everything — savings and debt payments are planned “spending” too. The point is that every dollar gets a job before the month starts.
How it differs from other methods
Percentage methods like the 50/30/20 rule set broad targets. Zero-based budgeting goes line by line. It takes more effort, but it shows exactly where each dollar goes — useful if money seems to “disappear” every month.
Build one in 5 steps
- Write down next month’s take-home income. Only count money you are confident will arrive.
- List fixed bills with their real amounts and due dates (a bill calendar helps).
- Add savings goals — emergency fund and sinking funds for irregular costs.
- Give the rest to flexible categories such as groceries, fuel and fun, based on your tracked spending.
- Adjust until the total is exactly zero. If you are over, reduce flexible categories; if under, assign the leftover to a goal.
Illustrative example (made-up numbers): every dollar of $2,900 assigned
| Category | Planned |
|---|---|
| Rent | $1,100 |
| Utilities & phone | $190 |
| Groceries | $380 |
| Transportation | $210 |
| Insurance | $120 |
| Minimum debt payment | $95 |
| Emergency fund | $250 |
| Sinking funds (car, gifts) | $150 |
| Eating out & fun | $230 |
| Personal & household | $125 |
| Buffer for small surprises | $50 |
| Total | $2,900 — remaining: $0 |
Common problems — and fixes
| Problem | Fix |
|---|---|
| The plan breaks in week two | Base flexible categories on real spending, not hopes |
| Annual bills keep surprising you | Divide them by 12 and fund a sinking fund |
| Small overspends feel like failure | Keep a small buffer line and move money between categories when needed |
| It takes too long | Reuse last month’s plan and only change what is different |
When zero-based budgeting is a poor fit
If your income varies a lot, budget from a conservative baseline instead of the expected amount — our irregular-income guide shows how. If line-by-line tracking makes you give up, a simpler percentage method may serve you better. The best budget is the one you will keep using.
A simple weekly routine
- Once a week (10 minutes): compare what you spent in each flexible category with what you planned.
- Move money, don’t ignore it: if groceries run over, take the difference from another flexible line, such as eating out, and write the change down.
- End of month: any money left in a category goes to a goal, such as your emergency fund — or rolls over if the category is a sinking fund.
Zero-based vs. 50/30/20 at a glance
| Zero-based | 50/30/20 | |
|---|---|---|
| Effort | Higher — every dollar assigned | Lower — three broad targets |
| Control | Very detailed | Broad |
| Best for | People whose money “disappears”, or who are paying down debt | Beginners who want a quick structure |
| Main risk | Feels tedious and gets abandoned | Too loose to spot problem categories |
Tools that work
You don’t need special software. A notebook, a spreadsheet or the CFPB’s free printable cash-flow budget tool all work. Some people use the “envelope” approach: they withdraw cash for a few flexible categories, such as groceries and fun, and stop spending when the envelope is empty. Choose whatever you will actually open every week.
Frequently asked questions
Does zero-based mean I have to spend everything?
No. “Zero” means every dollar has a job. Savings, debt payments and a small buffer are jobs too.
What if I get paid every two weeks?
Build the plan per paycheck: assign each paycheck to the bills due before the next one, then to savings and flexible spending. A bill calendar makes this much easier.
How long does it take to set up?
Expect the first plan to take a while — perhaps an hour — because you are gathering numbers. After that, you can copy last month’s plan and only update what changed.
What if my real spending never matches the plan?
That is normal at first. Use two or three months of tracked spending to set realistic amounts, then adjust.
Next step
Before next payday, list your income and bills, then assign the rest until you reach zero. The CFPB’s free cash-flow budget tool (below) is a good printable worksheet.
Sources
- Consumer Financial Protection Bureau — Creating a cash flow budget (Your Money, Your Goals tool) (accessed Oct 29, 2026)
- Consumer Financial Protection Bureau — Monthly budget worksheet (accessed Oct 29, 2026)